Anthropic IPO: Is ANT Stock Worth Buying? Prospectus Breakdown
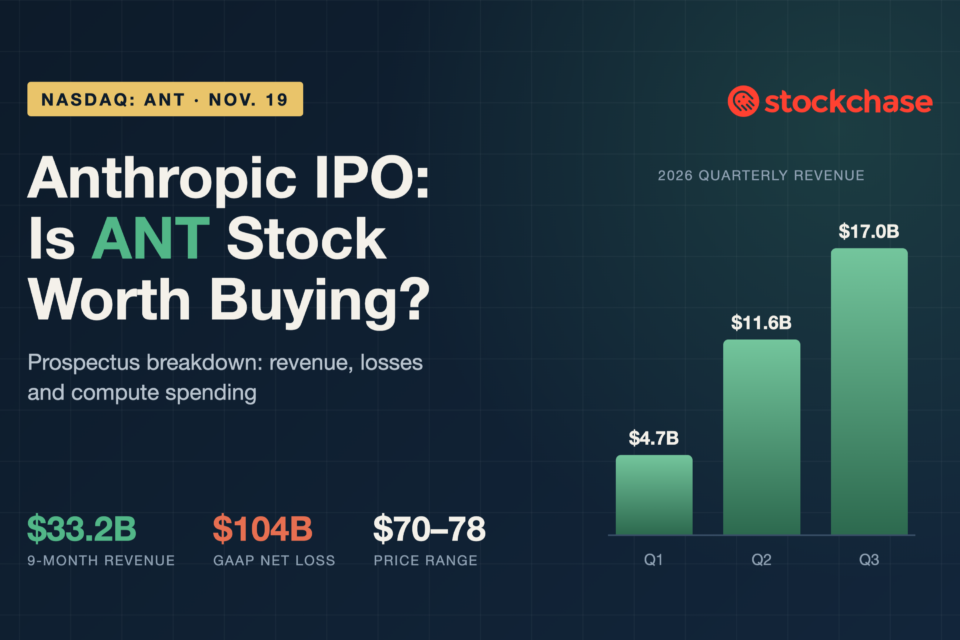
Anthropic, the biggest IPO in stock market history, is scheduled to go public on Thursday, November 19 under the ticker ANT on the Nasdaq. The valuation is projected to be at $1.3-1.4 trillion (some say $1.5 trillion), with a targeted raise up to $64.4 billion (all figures in this article in USD). Based on figures from the current road show, that valuation is based on a price range for ANT at $70-78 per share and an offering size of $57.75 billion to $64.35 billion. Will Anthropic achieve that?
Let’s look at their prospectus, starting with revenue. In 2023, it was $41 million, in 2024 $386 million, 2025 $4.59 billion (with a B), and in the first nine months of this year it was $33.2 billion. Breaking that down, Q1 2026 saw $4.73 billion, Q2 $11.56 billion and Q3 $16.96 billion. Yes, growth has been exponential, but consider that the company’s net loss in 2023 was about $1.5 billion (with a B).
Anthropic’s net loss widened to $80.7 billion in the first half of 2026, mostly caused by an increase in the fair value of bonds convertible into shares. A year earlier, that loss stood at $13 billion. Also in the first nine months of 2026, its GAAP net loss was $104 billion vs. $5.6 billion adjusted net income. More on this later.
So what about revenues? The company states that its Q3 revenue spiked 47% to $16.96 billion over the previous quarter. From Q1 to Q2, revenue more than doubled to $11.6 billion. The numbers are impressive per se, but also represent slowing growth which concerns some investors. Also note that ANT became profitable for the first time only in Q2 this year. Adjusted operating margin was positive again in Q3, and the company is profitable this year on an adjusted basis, though not on net income. ANT is far more profitable than OpenAI.
Future spending will be huge and will climb. Anthropic’s prospectus states high infrastructure investments in the coming years to keep growing. We’re talking hundreds of billions of dollars the company will spend on compute from partners like Amazon, Google and Broadcom. For example, starting next month, Anthropic will drop more than $3 billion a month to run SpaceX compute, part of an overall $120.5 billion deal running through 2029. Anthropic plans to spend $900 billion in compute and infrastructure, with half of that by the end of 2030 and $70 billion in the next 12 months. To compare, Anthropic spent around $9 billion in these areas in the first half of 2026, and $2.3 billion a year before that. Anthropic plans to spend 45-50% of its revenue on compute and infrastructure, a further 7-10% on sales and marketing, and the rest on labour and all else.
There is a payoff…sort of. As noted, Anthropic became profitable for the first time in Q2 this year, but also carried a net loss of $80.7 billion in the first half. That came from a non-cash accounting charge, the result of the rising valuation of convertible notes and equity agreements with major backers, including the above-mentioned Amazon and Google. As Cramer explains it, the key to this discrepancy is that instead of Anthropic paying these big partners big, ANT has instead given them stakes in the company, which appear on the balance sheet as non-cash charges. Essentially, ANT gets compute resources from them, but spends billions with those companies in exchange.
As for free cash flow, Anthropic generated $3.5 billion of it on $16.3 billion in revenue during the first half of 2026, reversing their previous cash burn. For Q3, the company reported positive free cash flow and $16.9 billion in revenue during the third quarter of 2026, alongside $6.6 billion in operating cash flow for the first nine months of the year. The problem: heavy capex could drain that free cash and turn it into a deficit.
So, ANT is profitable in 2026 on an adjusted basis but not on net income. Further, the company is more profitable than peers, namely OpenAI. ANT reported its first positive cash flow from operations this year, but spent much more on investments than what it generated from operating income. All this leaves a 35% adjusted operating margin in the long run, but Anthropic must grow a lot to justify the enormous costs to develop AI.
That’s the bottom line. Undoubtedly, the IPO will make a huge splash and raise a record-breaking fortune. Shares will likely exceed the $78 target and trade above $100, if ANT replicates SpaceX’s debut. But will ANT’s share price hold and rise in the weeks that follow?
Anthropic is a risky bet. Success depends on strong growth balancing heavy expenses. If that balance falters, then Anthropic is in trouble. However, Anthropic has momentum and decent metrics. ANT is not for casual investors, but for those who can stomach risk.
Trending Now
Anthropic IPO: Is ANT Stock Worth Buying? Prospectus Breakdown

You may also like